Swiss Franc (CHF) to Euro (EUR) converter
Track the exchange rate
of the swiss franc / euro exchange rate
- Open
- …
- High
- …
- Low
- …
Rates shown for information only. Sources: European Central Bank daily reference rates (via Frankfurter) and CurrencyLayer.
- Over one year
- − 0.1 %
- Over 3 months
- − 1.0 %
- Over 30 days
- + 1.0 %
Where the rate sits over one year
1.07380
One-year low 1.05510 One-year high 1.11010
Figures computed on 11.10.2026 from European Central Bank reference rates.
The technical picture
of the CHF / EUR rate
Over twelve months, the CHF / EUR rate ends up almost where it started. It currently sits around the middle of that range.
The CHF / EUR rate has been climbing over the past thirty days. The move is there but modest, and does not yet settle the quarter.
The franc gains against the euro
French debt once again weighed on the euro during the week. After starting lower due to renewed risk appetite, the Swiss franc regained its safe-haven appeal late in the week against a pressured European currency. Already on Monday, the euro was among the weakest G10 currencies amid protests in France, the announcement of a nationwide strike on November 5, and the calling of snap elections in Spain.
The brief respite seen on Tuesday for OATs and the single currency did not last. By Wednesday, French yields resumed their rise following denied rumors regarding Paris’s short-term debt issuance, leaving the euro trailing behind.
European monetary policy and French risk under scrutiny
On Thursday, the minutes from the European Central Bank’s September meeting revealed a more dovish tone than expected. The account indicated that the orderly rise in long-term rates supports the monetary policy stance and could weigh on policy rate decisions. The 10-year yield spread between France and Germany narrowed to 136.1 basis points, before the euro lost ground again on Friday in the absence of new developments in Paris. The next benchmark for the eurozone is set for November 5 with the planned nationwide strike in France.
Written from the weekly analysis by Jean-Marc Sabet, published on 11.10.2026. Read it in full: Paris tousse, l’euro s’enrhume.
Your money deserves better
than your bank’s rate
Most banks add hidden margins on top of the real exchange rate. It seems free, but it is not.
At b-sharpe, we show you a clear, no-surprise rate with minimal fees. You see what you pay, and what you gain.
AMOUNT TO EXCHANGE



The data provided are for information purposes only and do not include subscription offers. Discover how we compare prices.
Today’s exchange rate
CHF to EUR
CHF to EUR conversion table
Conversion CHF – EUR
Conversion EUR – CHF
Our popular CHF converter pairs
CHF
 USD
CHF
 GBP
CHF
 AED
CHF
 AUD
CHF
 CAD
CHF
 HKD
CHF
 ILS
CHF
 JPY
CHF
 MXN
CHF
 NOK
CHF
 NZD
CHF
 SEK
CHF
 SGD
CHF
 ZAR
CHF
 PLN
CHF
 THB
CHF
 MAD
CHF
 DKK
CHF
 CZK
CHF
 RON
CHF
 SAR
Our popular EUR converter pairs
The history of the Swiss
franc and the euro
The Swiss franc, born of the unification of the cantons
Before 1850, Switzerland had more than eight hundred different currencies: every canton, every town, sometimes every abbey struck its own. The federal coinage act of 7 May 1850 put an end to that and created the Swiss franc, aligned on the French franc of the day. In 1865 the country joined the Latin Monetary Union, alongside France, Belgium and Italy, which set the weight and fineness of silver coins.
The Union fell apart between the wars, but the franc outlived it. The Swiss National Bank, founded in 1907, took sole charge of it. The stability it gave the franc made it a safe-haven currency: in times of tension capital moves into it and it appreciates, to the point that the SNB capped its rate against the euro from 2011 to 2015.
The euro, the story of a common currency
The euro was not born of an internal unification but of a treaty. Signed at Maastricht in 1992, it set the convergence criteria (debt, deficit, inflation, interest rates) that states had to meet in order to join. The currency first existed without existing: from 1999 to 2002 it was a unit of account while francs, marks and lire kept circulating.
Coins and notes arrived on 1 January 2002 in twelve countries. Twenty use them today. The European Central Bank, in Frankfurt, holds monetary policy alone, while budgets remain national. That asymmetry explains a good part of the area’s crises since 2010 and the euro’s sensitivity to interest rate gaps.
Convert your CHF to EUR
with b-sharpe
- Account creation
- Sending funds
- Delivery within 24 hours
excluding weekends and public holidays
- NO account opening fees
- NO account management fees
- NO account closure fees
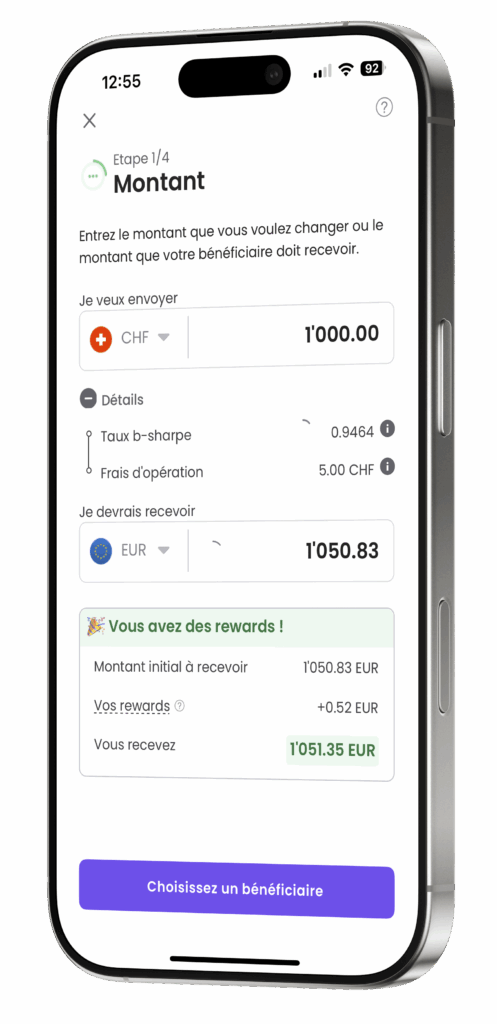
Frequently asked questions about CHF / EUR exchange
The CHF / EUR converter
6 questionsWhat is the b-sharpe CHF / EUR currency converter for?
The b-sharpe CHF / EUR currency converter displays the interbank market rate in real time, updated every 5 minutes. This is the gross rate without any added fees, used as a reference to evaluate the real value of your exchange. You can also view the 30-day graphical evolution to visualise rate volatility. To convert your CHF to EUR at the best rate, visit change your currency.
When is the best time to exchange CHF for EUR?
No one can predict with certainty how the CHF / EUR rate will move: there is therefore no ideal moment in absolute terms. The rate moves continuously during the week, driven by economic news and by decisions of the SNB and the ECB. Rather than trying to catch the peak, you can set a target rate and activate an alert to be notified as soon as it is reached. When the rate suits you, you can lock it for 48 hours from your client area. If you are exchanging a large amount, splitting it into several transactions also helps smooth out the effect of fluctuations.
Is the CHF / EUR rate updated in real time?
Yes, the CHF / EUR rate displayed on the converter is updated in real time, based on the interbank market. This rate reflects the balance between supply and demand for Swiss francs and euros on the financial markets at the moment you run your simulation. It can therefore change from one check to the next, sometimes within just a few minutes. To take a step back, the 30-day chart shows you recent rate movements. And if the current rate suits you, you can lock it for 48 hours once your conversion has been initiated.
What is the difference between the interbank rate and the bank rate?
The interbank rate is the rate at which banks exchange currencies with each other, without a margin: it is the one shown on this converter. The bank rate is the one your bank actually applies when you exchange your CHF for EUR. The gap between the two is the exchange margin, which can reach 2% depending on the institution and generally does not appear as a separate fee line. In practical terms, on 5,000 CHF converted, a 2% margin means the equivalent of 100 CHF less on arrival. At b-sharpe, the rate applied is based on the interbank rate, with transaction fees from 0.12% displayed before you confirm. These gaps vary from one provider to another, as our exchange fee comparison shows.
Does the CHF / EUR rate displayed on the converter include fees?
No. The rate displayed on the b-sharpe converter is the interbank rate, i.e. the market rate without any added fees. This is the purest reference value, the one banks use among themselves. The rate you will get when making a real exchange through b-sharpe includes transaction fees from 0.12%, which allows savings of up to 80% compared to banks.
Does the converter take weekends into account?
The foreign exchange market is closed at weekends: rates displayed on Saturday and Sunday are therefore indicative and non-contractual. They correspond to the last known rates before the close, and the rate may have moved by the time the market reopens. If you fix a rate on Friday, the 48-hour window applies as normal. Conversions then resume on Monday morning, when the market reopens. So as not to miss a movement at the start of the week, you can set an alert on the rate threshold you are interested in.
Exchanging CHF / EUR with b-sharpe
8 questionsHow can I repatriate my cross-border salary in euros?
If your salary is paid in Swiss francs, you need to convert it into euros to use it in France. If you go through your bank, the conversion includes an exchange margin that is often invisible and can reach 2%. With b-sharpe, you do not need a bank account in Switzerland: you receive a Swiss IBAN in your name, into which your employer pays your salary directly. Your CHF are then converted based on the interbank rate, with transaction fees from 0.12% that decrease as the amount increases, and transferred to your French account, generally within 1 to 2 working days. If you already have an account in Switzerland, you can also keep your salary there and transfer your CHF to b-sharpe yourself whenever you choose. On a salary converted every month, the difference adds up: a 1% gap on 6,000 CHF represents around 60 CHF per month, or 720 CHF over a year.
Why convert swiss franc with b-sharpe rather than my bank?
Banks often apply hidden margins of up to 2% on the exchange rate. With b-sharpe, fees start from 0.12% and are always based on the interbank rate. In addition, you always have visibility on the exact amount you will receive before confirming. This saves you up to 80% on your transaction fees.
Can I lock the rate I see now?
The online converter displays the market rate in real time without fees, for simulation purposes. To lock a rate and initiate a transaction, simply create a free account on b-sharpe. From your client area, you can lock your rate for 48 hours. You will then have full visibility of the final amount to be received, including our transaction fees (from 0.12%): no surprises, you receive exactly the displayed amount. You can also set up rate alerts to be notified when the CHF / EUR rate reaches your desired threshold.
How long does a transfer from Switzerland to Europe or internationally take?
Once your conversion has been confirmed and your funds received by b-sharpe, the transfer to Europe is executed within 24 to 48 working hours. For the rest of the world, allow 48 to 72 working hours. The timeframe starts when your funds are received, not when you initiate the transaction: this is the timeframe to bear in mind when planning for a deadline. Working hours exclude weekends and public holidays, which can extend a transfer initiated on a Friday. In all cases, the exact amount you will receive is displayed before you confirm.
Is my money safe?
b-sharpe is a Swiss financial intermediary, affiliated to SO-FIT, a self-regulatory organisation (SRO) recognised by the Swiss Financial Market Supervisory Authority (FINMA). In practice, an SRO checks that its members comply with their legal obligations under Swiss law, particularly in the fight against money laundering. Your funds are received in a bank account domiciled in Switzerland, separate from b-sharpe’s own funds. Your money is therefore never mixed with the company’s. These funds are also covered by insurance of 5 million CHF against fraud and hacking.
Is there a minimum amount to exchange currencies?
No, there is no minimum amount required for a one-off transaction. You can therefore exchange a small sum just as easily as a large amount. You only pay when you make an exchange: there are no fixed fees and no subscription. Transaction fees start from 0.12% of the amount, which makes them proportional to the sum you convert. Whatever the amount, you see the exact sum you will receive before confirming.
Can I set up a recurring CHF/EUR transfer?
Yes, by combining two elements. On the one hand, you top up your Swiss b-sharpe IBAN regularly: either your employer pays your salary directly into it, or you set up a standing order from your own bank. On the other hand, your CHF are automatically converted into euros each time they are received, then transferred to your account in France, with no transaction to restart every month. b-sharpe never debits anything from your accounts: you remain in control of the transfer order. In return, the rate applied is the market rate at the moment the funds arrive. If you prefer to choose when each conversion takes place, convert manually with the help of rate alerts.
How do I create a b-sharpe account?
Registration is free and without commitment: you only pay when you carry out a currency exchange. If you are an individual, the whole process is done online in less than 10 minutes. If you are a business, you complete your details in 2 minutes, then an account manager will contact you within 24 hours. Once your account is open, you can lock a rate for 48 hours and set up rate alerts from your client area.